
The world’s government bond markets have spent the summer and early fall undergoing their sharpest repricing since the aftermath of the 2008 financial crisis. Long-term yields across the United States, the United Kingdom, Japan, and much of Europe have climbed to multi-year, and in some cases multi-decade, highs. So far, however, most analysts describe the move as orderly rather than disorderly, a distinction that matters a great deal for investors, borrowers, and policymakers alike.
Several forces are converging to push yields higher. Renewed tensions in the Middle East and disruptions to Russian refining capacity have pushed energy prices up, fuelling inflation expectations. Allianz Research notes that this dynamic accounts for a meaningful share of the recent move, with European inflation ticking up to 3.3 per cent in August.
At the same time, heavy government borrowing needs, particularly in the United States, are colliding with investor demand at a moment when fiscal deficits show little sign of narrowing. J.P. Morgan Asset Management’s chief global strategist, David Kelly, frames this as a break from the low-rate era that followed the financial crisis, when quantitative easing and near-zero policy rates helped keep yields artificially suppressed. He estimates that the United States will run a fiscal 2026 deficit of more than $2 trillion, or over 6.4 per cent of GDP, while federal debt is on track to reach 120 per cent of GDP by the middle of the next decade.
Political dynamics are adding to the pressure. In Europe, investors are demanding a higher premium from countries such as France and Italy, where fragmented governments make credible deficit reduction harder to deliver. In France, that has pushed the spread between French OATs and German Bunds toward its widest level in years.
Japan presents a different dynamic. A central bank that is likely to raise rates further is drawing capital home. That shift could have global implications, as Japanese investors hold roughly US$3 trillion in Treasuries and remain an important source of demand at U.S. Treasury auctions.
None of this amounts to panic. Allianz Research notes that bid-ask spreads and auction demand remain healthy, even as concerns about the long-term sustainability of government debt loads become harder to ignore.
Canada offers a useful point of comparison. Thirty-year Government of Canada bond yields have risen about 24 basis points this year to roughly 4.16 per cent, a far more modest increase than in the United States, where yields have reached 5.24 per cent, or the United Kingdom, at 5.77 per cent. Japan’s 30-year bond yield has also risen sharply this year and is near multi-decade highs, at nearly 4 per cent.
Canada’s relative calm reflects several factors. Its combined federal and provincial deficit is estimated at about 3.5 per cent of GDP, compared with roughly 6 per cent in the United States. Canada’s stimulus mix is also weighted more toward infrastructure than the tax-driven spending associated with the U.S. artificial intelligence boom.
Canadian corporate credit has also held up well, supported by a bond market weighted toward relatively conservative issuers in sectors such as financials and energy, as well as strong demand from institutional investors such as pension funds. That stands in contrast to the heavier volume of AI-related debt weighing on U.S. credit markets.
Implications for Canadian Borrowers
Fixed-term mortgages are priced off the Government of Canada bond curve plus a funding spread that reflects credit risk and cost of capital. The comparatively modest rise in Canadian yields should translate into less upward pressure on renewal and new mortgage rates than the headlines out of the United States might suggest. Canada is not insulated, however. Global yield moves affect Canada through cross-border capital flows, currency-hedging costs, and investor sentiment. A further rise in global yields would likely push Canadian rates higher as well, even if by a smaller amount.
Borrowers with fixed-term mortgages coming up for renewal over the next 12 to 18 months should plan for a rate environment that sits above the post-pandemic lows, even if Canadian rates remain more stable than the global sell-off narrative implies. Lenders, meanwhile, will want to watch fiscal developments in Ottawa and the provinces closely. Any erosion of Canada’s relative fiscal discipline could weaken any one of the key supports for its comparatively stable bond market and narrow the gap that currently favours Canadian borrowers.
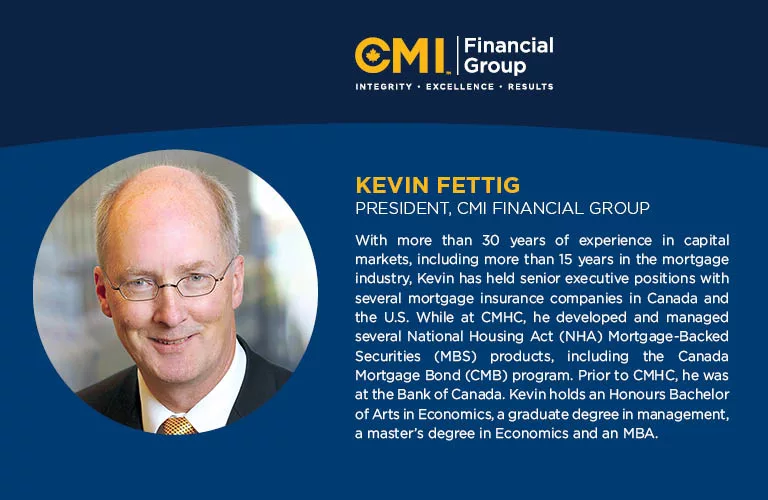
Independent Opinion
The views and opinions expressed in this publication are solely and independently those of the author and do not necessarily reflect the views and opinions of any person or organization in any way affiliated with the author including, without limitation, any current or past employers of the author. While reasonable effort was taken to ensure the information and analysis in this publication is accurate, it has been prepared solely for general informational purposes. Any opinions, projections, or forward-looking statements expressed herein are solely those of the author. There are no warranties or representations being provided with respect to the accuracy and completeness of the content in this publication. Nothing in this publication should be construed as providing professional advice including investment advice on the matters discussed. The author does not assume any liability arising from any form of reliance on this publication. Readers are cautioned to always seek independent professional advice from a qualified professional before making any investment decisions.
